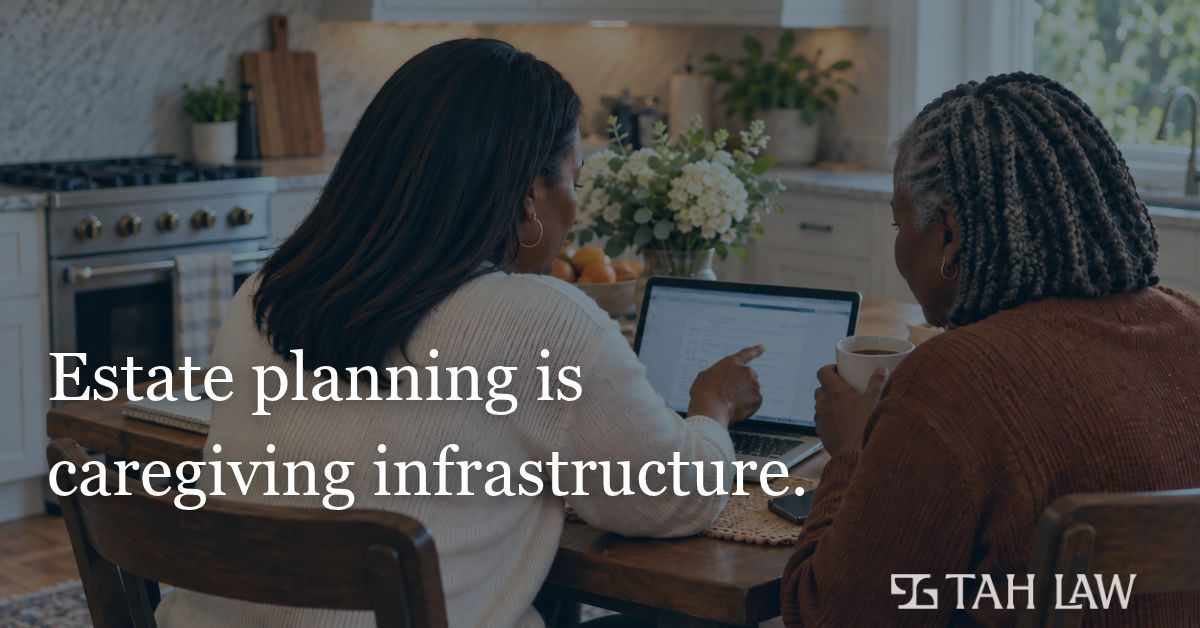
Estate planning is caregiving infrastructure
The hospital wants to know who’s making decisions. The bank wants to know who’s authorized. The doctor’s office won’t talk to you without a name on file.
If you’ve ever been the one everyone calls, you know these conversations. They rarely arrive at a convenient moment. They come in the middle of a workday, a school pickup, a parent’s appointment that ran long. When the right documents exist, each one takes a few minutes. When they don’t, the person doing the caring can end up asking a court for permission to keep doing it.
National Estate Planning Awareness Week runs October 19–25, 2026. We’re spending it on estate planning for caregivers, and on a reframe.
Estate planning isn’t paperwork about dying
Most people file estate planning under “eventually,” next to the will they keep meaning to write. That framing misses most of what a plan does.
Some of the most important documents have nothing to do with death. They cover the stretch of life when someone you love needs help, or when you do. They decide who can pay the mortgage, who talks to the doctors, and who can find what they need without a court order.
That’s infrastructure. Like roads and power lines, nobody notices it until it’s missing, and it works best when it’s built before anyone needs it.
Estate planning is an act of love. It’s also what allows the people you love to show up for you.
1. A financial power of attorney: authority while you can still choose
Being someone’s caregiver doesn’t give you authority over their money. Love is not a legal document.
You can manage every appointment for someone you love and still be unable to pay their mortgage from their account, speak with their insurer, or handle their retirement funds. Without a financial power of attorney, getting that authority can mean a guardianship case in court.
In Maryland, a written power of attorney is generally durable, meaning it keeps working if you become incapacitated, unless the document says otherwise. That’s the point of it. The decisions worth making carefully are in the details:
- Who would you trust with your finances, and who’s the backup?
A poorly structured power of attorney can become a blank check. A thoughtful one becomes a steady hand.
One helpful gut check: if you’re hesitant to hand someone that power today, you won’t want them holding it when you can’t weigh in.
2. A health care proxy and advance directives
Without this document, a bedside medical crisis can quickly become a bedside family crisis.
A Maryland advance directive lets you name a health care proxy, the person who speaks with your doctors when you can’t. It also puts your treatment wishes in writing, so no one has to guess.
Fewer people know that Maryland law also recognizes a mental health advance directive. It lets you plan ahead for a mental health crisis: who can make decisions, which providers and facilities you prefer, which medications have or haven’t worked for you, and who should be told.
Whether you’d be the one getting the call or the one who needs someone to call, these documents protect both sides of that relationship.
One way to start the conversation: “If something happened and you couldn’t speak for yourself, who would you want talking to the doctors? Have you told them?”
It doesn’t have to be heavy. It just has to be honest.
3. Beneficiary designations: the invisible plan
Your will doesn’t control everything you own. Retirement accounts, life insurance, and payable-on-death bank accounts generally pass to whoever is named on the beneficiary form, not whoever is named in your will.
That form may be one you filled out at orientation for a job you left years ago. It may name someone who has since passed, or a child who was a toddler when you signed it, or no one at all.
This is also the one item here you can review on your own. Many account portals show the current designation in a few clicks, and if a name surprises you, you’ve found something worth fixing.
4. Access: a plan no one can find
A signed will in a drawer no one can find is almost as risky as no will at all. The same goes for a power of attorney nobody knows exists, or an advance directive saved on a laptop no one can open.
Infrastructure only works if people can reach it. The people you’re counting on need to know three things:
- that your documents exist
5. When “equal” and “fair” aren’t the same thing
Three siblings. One moved back home and spent six years managing their mother’s appointments. One sent money every month. One lives across the country and called on Sundays.
The will divides everything in thirds.
Is that fair? It might be. Many parents choose equal shares on purpose, and that’s a legitimate choice. The damage comes from leaving the children to guess at the reasons after their parent is gone.
If you’re weighing an unequal plan, or an equal one you know will be questioned, decide on purpose:
- Put your reasons in writing. A letter alongside your plan, prepared with your attorney so it supports your documents rather than contradicting them.
Equal is a math problem. Fair is a values question. Your plan should answer the one you actually mean.
What changes when it’s done
Most people don’t skip estate planning on purpose. They keep meaning to get to it, usually after everyone and everything else is handled.
Here’s what the turn can look like. You sit down with an attorney who explains each document in plain language, asks about the people in your life before the property, and works through the decisions above one at a time. Each choice gets smaller once it has a name.
What you leave with isn’t a stack of paper. It’s a plan that tells your bank, your doctors, and your loved ones the same thing: this person is allowed to help.
After that, the phone calls are just phone calls. The caregiver keeps caring without asking anyone’s permission, and becomes the one telling a friend, “It’s not as hard as you think.”
Legacy doesn’t protect itself. Planning does.
Estate Planning Awareness Week is a great time to begin. It starts with a conversation. Click here to book an initial consultation.
This article is for informational purposes only and does not constitute legal advice. Reading it does not create an attorney-client relationship. For guidance specific to your situation, please consult an attorney.